


The Financial institution for Worldwide Settlements is renewing its criticism of stablecoins, questioning their credibility as on a regular basis cash as governments worldwide construct regulatory frameworks across the tokens.
BIS Basic Supervisor Pablo Hernández de Cos, a candidate to succeed European Central Financial institution President Christine Lagarde subsequent yr, argued that stablecoins don’t credibly operate as a way of cost at scale. He stated tokenized financial institution deposits provide a stronger different, Reuters reported on Friday.
“Tokenised deposits provide a extra direct path to harness tokenisation whereas preserving the financial system’s foundations,” de Cos stated.
The feedback come as regulators worldwide grapple with stablecoin adoption, whereas a brand new research from the BIS-linked Monetary Stability Institute (FSI) exhibits vital variations in how main markets regulate stablecoin issuers.
Stablecoins might decrease authorities borrowing prices
Hernández de Cos acknowledged that stablecoins might decrease authorities borrowing prices, an argument additionally made by US Treasury Secretary Scott Bessent.
However the impact might reduce each methods for shoppers. If clients transfer financial institution deposits into stablecoins, banks might face greater funding prices and go these bills on to households and companies by means of greater borrowing charges, Hernández de Cos stated.
Associated: Visa works with Upbit father or mother on stablecoin funds, AI commerce
He additionally pointed to restricted interoperability between stablecoin platforms and difficulties constantly making use of anti-money laundering controls. Rising use of US dollar-pegged stablecoins exterior the US might additionally undermine financial sovereignty and weaken home financial coverage, he stated.
Stablecoin issuers face completely different guidelines worldwide
The FSI research, revealed on Thursday, in contrast stablecoin rules within the US, European Union, United Kingdom, Hong Kong and Singapore, discovering substantial variations wherein entities might situation stablecoins and what different enterprise actions they will conduct.
The US and Singapore take comparatively restrictive approaches towards non-bank issuers. Below the US GENIUS Act, lending, staking, proprietary buying and selling and custody of third-party crypto belongings typically fall exterior the actions permitted for cost stablecoin issuers.
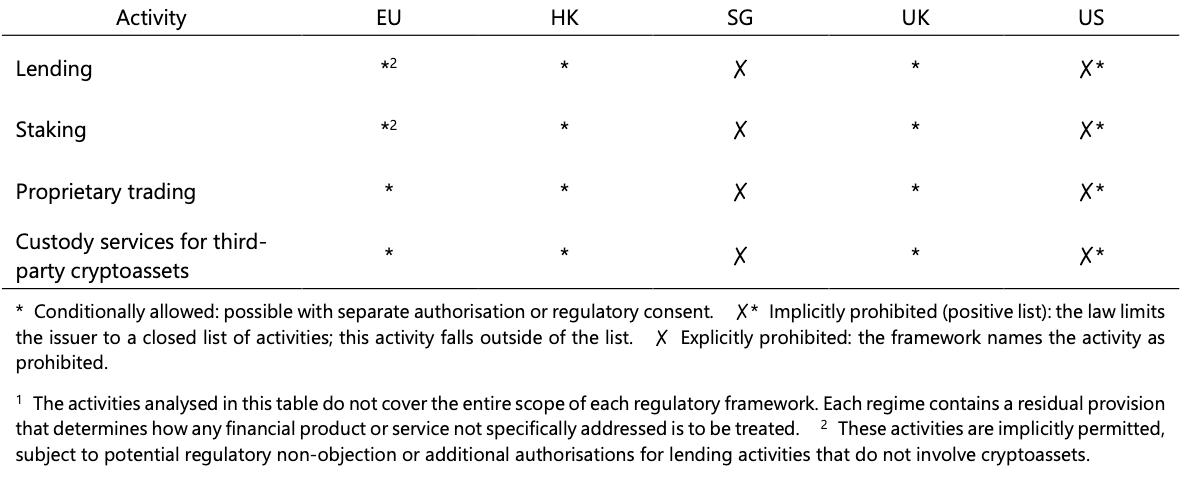
Stablecoin issuer guidelines throughout main markets. Supply: BIS
Hong Kong, the UK and EU take a much less restrictive strategy, permitting some further actions with separate authorization, regulatory consent or different relevant permissions.
The researchers additionally discovered that restrictions throughout all 5 jurisdictions apply to the issuing entity fairly than the broader company group, that means different group members can conduct actions that the stablecoin issuer itself can’t.
Journal: Korean financial institution faucets Ripple for funds, Pakistan opens crypto licensing: Asia Categorical

