


Superior Micro Gadgets Inc.’s first reinvention rebuilt the corporate. It was frankly about survival. Its subsequent reinvention should redefine the corporate. AMD’s resurgence over the previous decade got here from doing what many thought was inconceivable – rebuilding its processor franchise, taking significant share from Intel Corp., and restoring credibility by way of disciplined execution.
In our view, AMD’s subsequent chapter is basically completely different.
The corporate is now not making an attempt to defeat Intel in a mature x86 market. As a substitute, it’s positioning itself because the indispensable second platform in a quickly increasing synthetic intelligence infrastructure market – one the place Nvidia Corp. is more likely to stay the dominant participant for the foreseeable future.
That requires a completely completely different playbook.
AMD should proceed to construct world-class silicon. But it surely must do extra and guess its future on innovation, openness, heterogeneous computing, rack-scale programs, software program, networking, strategic acquisitions and relentless execution.
Our evaluation is AMD isn’t making an attempt to repeat the beat Intel playbook. It doesn’t have to.
Thesis: AMD gained its first turnaround by constructing a greater central processing unit. It should win its subsequent chapter — if it succeeds — by constructing a greater AI platform constructed round EPYC CPUs, Intuition accelerators, ROCm software program, rack-scale programs and an open ecosystem. We imagine Chief Government Lisa Su acknowledges that the “Beat Intel” playbook gained’t work in opposition to Nvidia. As a substitute, AMD is making an attempt to compress almost 20 years of ecosystem growth into only a few years by way of disciplined capital allocation, strategic acquisitions and relentless execution.
On this Breaking Evaluation, we’ll study how AMD engineered probably the most spectacular turnarounds in semiconductor historical past, why that method labored in opposition to Intel, why it gained’t work the identical method in opposition to Nvidia, and whether or not Lisa Su’s technique can remodel AMD from an x86 comeback story into one of many defining AI infrastructure platforms of the following decade.
Core premise
AMD’s first reinvention was a comeback story. It rebuilt the corporate by taking share from Intel in a mature x86 CPU market. However this subsequent reinvention is basically completely different. The target isn’t to beat Nvidia. In our view, that’s the mistaken technique to view the dynamics of the AI infrastructure enterprise.
Nvidia has constructed maybe the strongest AI infrastructure platform within the {industry} and we imagine it’s more likely to stay the dominant AI infrastructure provider for the foreseeable future. As a substitute, AMD’s problem is to outline what success seems to be like in a market the place Nvidia stays primary.
That’s a really completely different strategic drawback. The graphic beneath describes intimately the considering behind this premise.
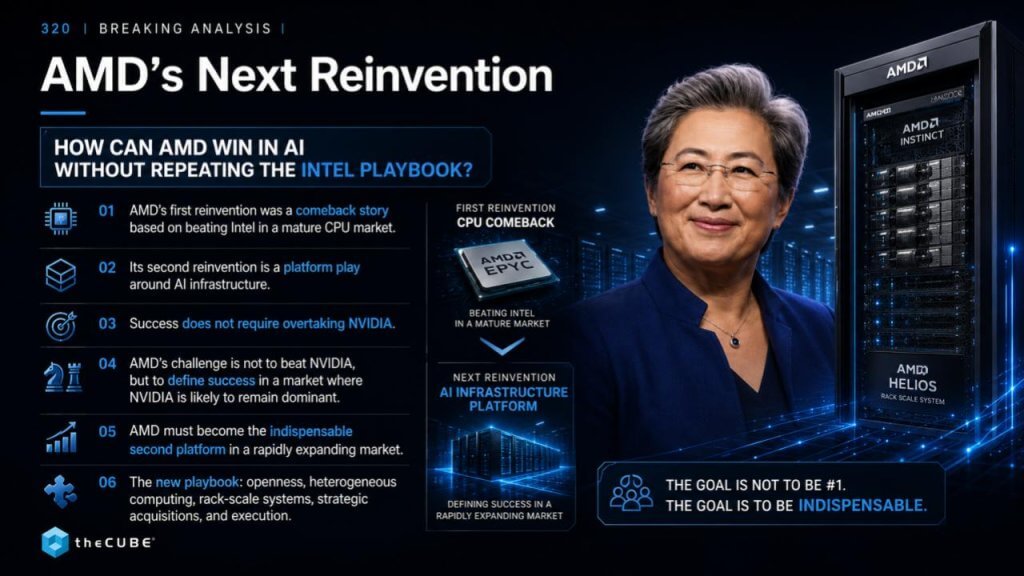
Fairly than making an attempt to displace the incumbent, AMD is positioning itself to develop into the indispensable second platform for AI infrastructure – constructed round EPYC CPUs, Intuition accelerators, ROCm software program, rack-scale programs akin to Helios, and a technique centered on openness, heterogeneous computing and disciplined execution.
To emphasise the important thing level of our evaluation – The objective for AMD isn’t to be No. 1. The objective is to develop into an indispensable various in a market the place provide is much outstripping demand for the foreseeable future — within the largest market within the historical past of tech.
To grasp AMD’s subsequent reinvention, it’s instructive to grasp its first transformation.
AMD’s turnaround was the consequence a convergence of three strategic selections, detailed beneath.
First, the corporate lastly let go of what had develop into a structural drawback. Founder Jerry Sanders famously mentioned, “Actual males have fabs.” Clinging to that built-in mannequin almost killed the corporate. However by spinning out GlobalFoundries in 2009, AMD embraced the fabless mannequin, permitting it to deal with design whereas finally leveraging TSMC’s manufacturing management.
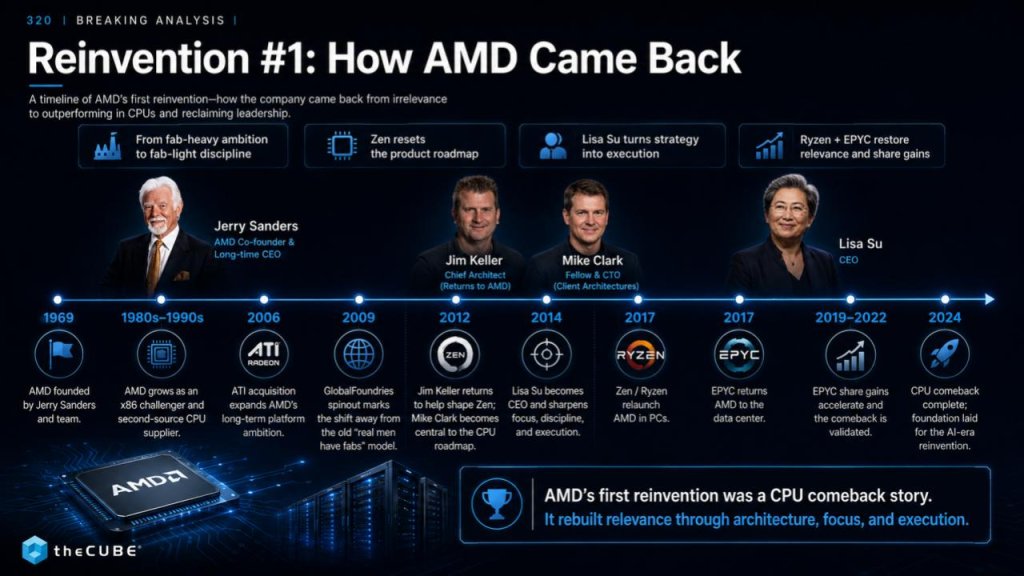
Second, AMD rebuilt its technical basis. Jim Keller, who by the best way is now the CEO of Tenstorrent — which was reportedly in talks with Qualcomm to be acquired for $10 billion — returned to assist architect Zen, with Mike Clark main the CPU micro-architecture effort. Zen was extra than simply one other processor. It utterly reset AMD’s roadmap and restored the corporate’s engineering credibility.
Third, Lisa Su reworked a sound technique into disciplined execution. After turning into CEO in 2014, on the younger age of 44, she persistently delivered on the roadmap, launching Ryzen into the PC market and EPYC into the info heart. Extra importantly, she rebuilt credibility with prospects, companions and Wall Road by doing what she mentioned she would do.
The important thing level is AMD’s first reinvention wasn’t nearly a CPU comeback. It rebuilt the corporate by way of structure innovation, focus and execution – and laid the muse for all the pieces the corporate is making an attempt to perform in AI in the present day.
Why AMD’s assault on Intel was so profitable
AMD’s first reinvention succeeded as a result of it attacked a really particular drawback. Intel’s manufacturing management started to falter simply as AMD’s architectural execution improved dramatically.
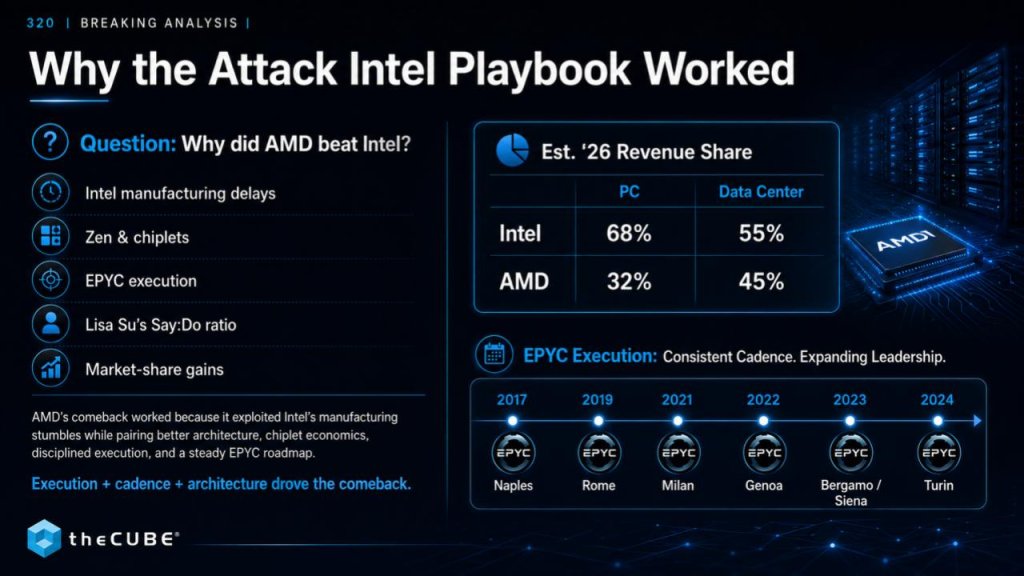
The Zen micro-architecture reset the corporate’s CPU roadmap. The selection of chiplets allowed AMD to present its prospects selection, financial benefit and engineering flexibility. This was a giant deal because it lured prospects away from a faltering Intel.
Then EPYC execution got here with outstanding consistency, delivering a predictable cadence of recent merchandise into the info heart from the beginning of Naples in 2017 to Milan and Genoa in the course of the pandemic into Venice (not proven on the slide above), which will likely be highlighted at AMD’s Advancing AI occasion this coming week. It’s the most recent in an extended line of world-class processors.
Say:Do – Maybe most significantly, Lisa Su established a popularity for execution. Quarter after quarter, technology after technology, AMD did what it mentioned it was going to do. That restored confidence with prospects, companions and buyers.
The consequence was a outstanding comeback.
Because the slide above reveals, AMD has clawed again significant share in each PCs and the info heart – specifically roughly 55% income share within the x86 knowledge heart market, whereas sustaining one of many {industry}’s most disciplined product roadmaps.
However as we’ll focus on momentarily, each one in every of these benefits performed out inside a comparatively mature x86 market. Structure. Execution. Course of. Worth-performance. These have been the levers AMD pulled.
The following chapter will likely be completely different, as a result of the market itself has basically modified.
How Wright’s Legislation and the amount conundrum helped AMD beat Intel
Earlier than we dig into the basic modifications out there, we wish to evaluation in additional element, the core challenges Intel confronted, which AMD exploited. Intel’s troubles began to point out up early final decade, properly earlier than most observers realized. The chart beneath reveals x86 volumes peaking on the orange line (as PC volumes peaked) 365 million items (circa 2011). We noticed a “lifeless cat bounce” in the course of the pandemic, however the lengthy gradual decline of x86 continues in the present day. It stays a multi-hundred-million-unit market; nevertheless, the blue line represents Arm unit volumes. Discover this can be a double Y-axis chart and the Arm items are in billions whereas x86 is within the thousands and thousands. So Arm wafer volumes are 10 instances these of x86, which confers important price benefits to TSMC. So Intel was preventing a two-front struggle – with AMD consuming share within the core x86 market, and Intel’s foundry at a big price drawback relative to TSMC.
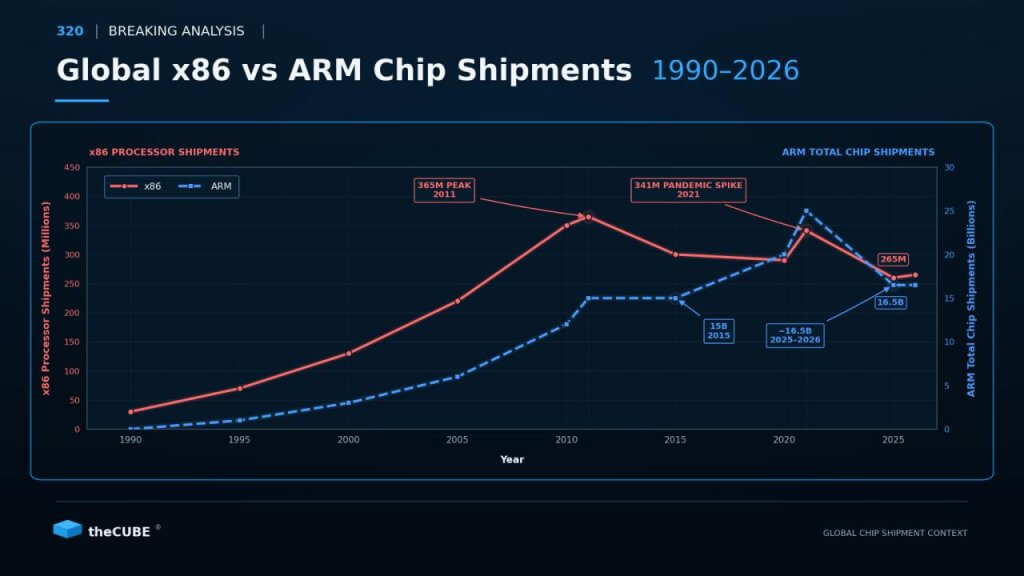
The vital level isn’t merely that PC volumes peaked round 2011. It’s that after x86 stopped being the amount engine of the semiconductor {industry}, the economics modified. Wright’s Legislation tells us that manufacturing prices decline by a continuing as cumulative manufacturing doubles. As Arm grew to become the amount structure by way of smartphones and embedded gadgets – and fabless corporations more and more relied on exterior foundries – the middle of gravity shifted. AMD’s first comeback occurred simply because the outdated x86 economics have been starting to plateau. That’s vital to grasp since you shouldn’t consider the AI period as one other CPU cycle – it’s a completely new quantity curve.
Now in some methods, relative to Intel, AMD has completely different challenges round x86 but in addition faces comparable headwinds. AMD doesn’t have the foundry dedication (and the drag on its P&L) that Intel has; however the market is shrinking for each corporations. It should develop into more and more troublesome for AMD to realize share at a charge comparable because it has prior to now, particularly as Intel will get its monetary act collectively underneath CEO Lip-Bu Tan.
A parallel play AMD can run in our view is to be a bridge from x86 to the AI manufacturing facility period. As a result of it has a robust place in x86 knowledge heart and is forward of Intel in AI, it is able to impact that transition. After all, a wildcard is the deal that Intel has with Nvidia as a part of its $5 billion funding in Intel. Particularly, we’re referring to the built-in dual-chip structure optimized for AI knowledge facilities.
The important thing level is, within the fullness of time, we predict that a lot of in the present day’s software program stack performance, constructed round general-purpose x86 programs, will likely be re-architected round fashionable AI infrastructures. If and when this evolves, unbiased software program distributors will likely be compelled, for financial and performance causes, to port their software program to AI programs – CUDA, ROCm and the like — and this is a chance for AMD to earn money regardless of the x86 unit quantity decline.
New guidelines for AI infrastructure
This graphic beneath is probably crucial in in the present day’s Breaking Evaluation.
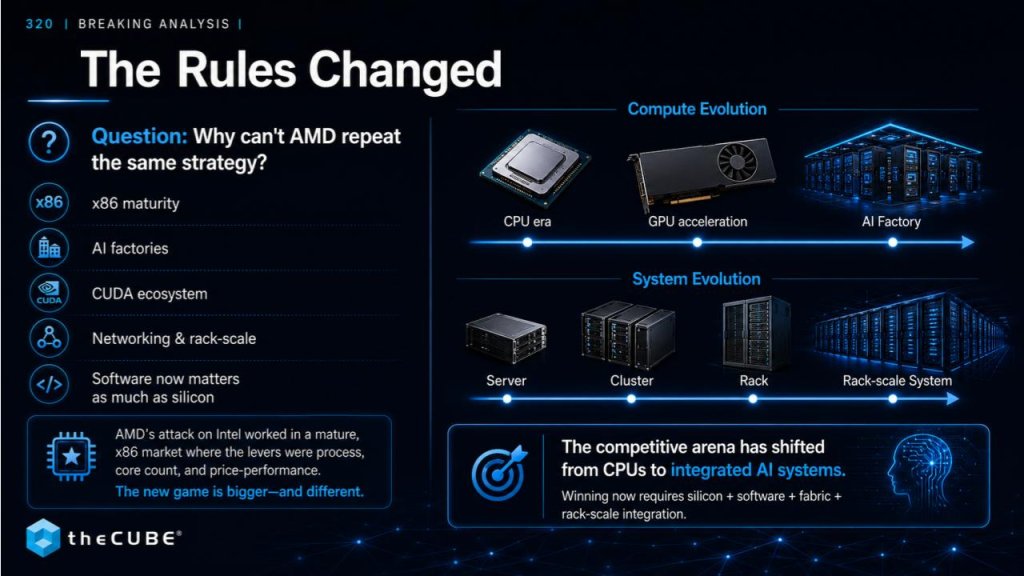
AMD’s first turnaround labored as a result of it attacked a mature x86 market the place the aggressive variables have been properly understood – course of know-how, CPU structure, core counts, energy effectivity and price-performance. However the guidelines have modified. The market AMD is coming into in the present day bears nearly no resemblance to the market the place it defeated Intel. The battleground is now not the CPU. CPU performs an vital position. But it surely’s a job within the bigger AI manufacturing facility.
With AI, profitable in semis has shifted from designing the quickest and greatest value/efficiency processor to delivering the perfect built-in system. Which means integrating silicon, software program, networking and a developer ecosystem into a complete system. In the end, this drives the economics of AI itself.
In different phrases, the idea of competitors has shifted from particular person elements to finish platforms. That’s the place Nvidia’s benefit turns into rather more troublesome to beat. Nvidia’s lead isn’t simply silicon. It’s software program/CUDA, networking (Mellanox/NV-Hyperlink/Spectrum-X), rack-scale engineering, system integration and an ecosystem that has been rising for almost 20 years.
That’s why we imagine AMD can’t merely repeat the Intel playbook.
The sport itself has modified.
The CPU grew to become the middle of computing. The GPU grew to become the middle of AI. The AI manufacturing facility is turning into the middle of enterprise infrastructure. We’ve argued for a while that the AI manufacturing facility turns into the bodily basis of what we name the System of Intelligence. That’s additional up the stack than in the present day’s dialogue permits for, however that’s finally the place the client worth resides.
New guidelines, new playbook
So if AMD can’t repeat the Intel playbook, what precisely is the brand new mannequin? In our view, it may be summarized in three layers as proven beneath:
Construct the core;
Purchase the gaps;
Seed the ecosystem.
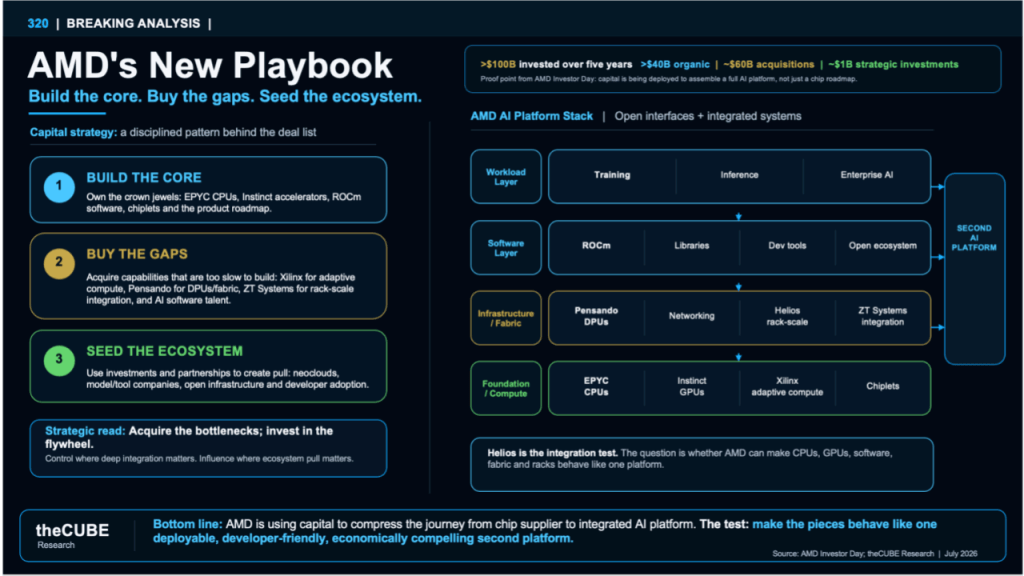
First, AMD is constant to make investments organically in what differentiates the corporate – EPYC CPUs, Intuition accelerators, ROCm software program, chiplet innovation and its product roadmap. Consider these because the crown jewels.
Second, the place time-to-market issues greater than constructing all the pieces internally, AMD has been remarkably disciplined with acquisitions. To wit:
Xilinx introduced adaptive computing by way of field-programmable gate arrays or FPGAs. Lisa Su at final yr’s investor day referred to as out $60 billion in acquisitions. Some $49 billion of that was Xilinx.
Pensando added DPUs and networking experience and is a important a part of the portfolio, which you’ll see at Advancing AI this coming week.
ZT Techniques will get AMD into rack-scale system integration ore shortly.
Fairly than buying adjoining companies, AMD has largely acquired bottlenecks – items that might have taken years to develop organically.
So you will have EPYC – right here comes Venice, Intuition, ROCm, Xilinx, Pensando, ZT Techniques….
We expect that’s precisely what’s taking place right here. AMD isn’t buying income. It’s buying the place it has bottlenecks. And it’s investing the place ecosystem flywheels could be created.
And that’s why there’s a giant push by AMD into open requirements.
Which brings us to the third layer – investments within the ecosystem. Which means software program, developer instruments, open requirements to facilitate partnerships with unique gear producers, hyperscalers and Neoclouds; and inspiring broader adoption of ROCm and an open AI software program stack.
Taken collectively, that is rather more than a silicon chip roadmap. It’s a platform technique. That’s an vital distinction as a result of we all know already that AMD can construct nice CPUs and let’s agree they’ll be construct wonderful graphics processing items too. The brand new sport and the true take a look at is whether or not it might probably make all of those items behave like a single, deployable platform.
In some ways, Helios turns into that integration take a look at. If AMD can combine CPUs, GPUs, software program, networking and rack-scale programs right into a coherent platform, then it has a reputable path to turning into the {industry}’s indispensable second AI platform.
If it might probably’t… then it dangers remaining a provider of wonderful elements in a market more and more outlined by full programs.
If you concentrate on what Lisa Su is doing, AMD is making an attempt to compress 20 years of ecosystem growth into 5 years of capital allocation. That is her technique to maneuver on the pace of Nvidia and never get left behind. In our view, the playbook of beating a wounded Intel has modified based mostly on the actions Lisa Su is taking. It’s clear AMD is transferring quickly in a brand new route.
How AMD stacks as much as the Nvidia gold normal
On the danger of oversimplifying issues, the slide beneath summarizes the place we imagine AMD stands in the present day relative to Nvidia.
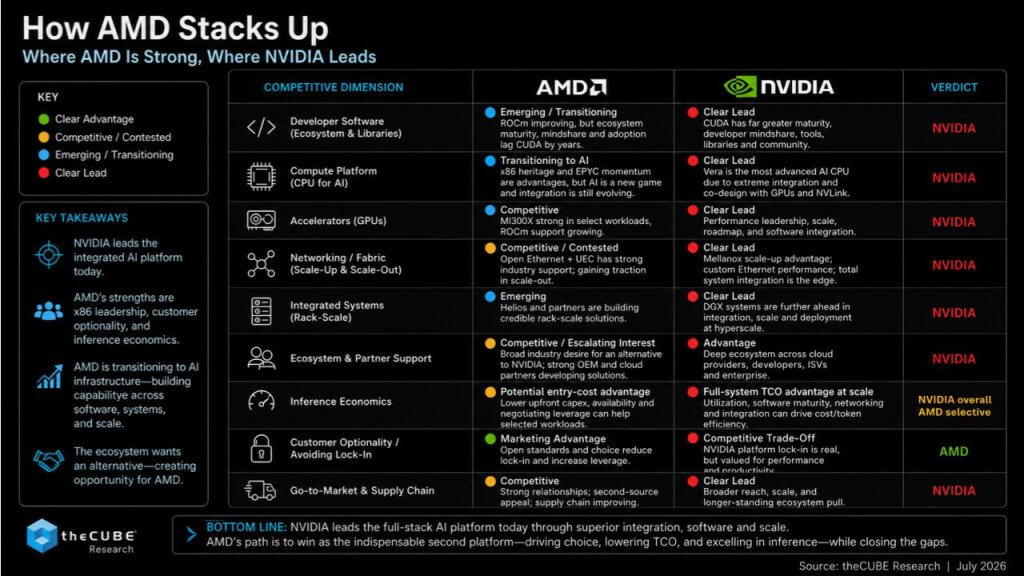
The primary takeaway is the plain: Nvidia leads the built-in AI platform in the present day.
Its benefit extends properly past GPUs. CUDA, developer mindshare, networking by way of Mellanox, NVLink and Spectrum-X, rack-scale programs,and almost 20 years of ecosystem growth create a formidable moat that AMD won’t erase and not using a main stumble from Nvidia. This we really feel is unlikely.
However that doesn’t imply AMD can’t do properly. Its strengths are completely different as is its worth proposition.
AMD stays a frontrunner in x86 server CPUs with EPYC. It has constructed a compelling portfolio by way of Intuition, Xilinx, Pensando and Helios. And maybe most significantly, it presents prospects one thing the market more and more values – optionality.
Our evaluation is that whereas Nvidia maintains clear management in software program, networking, built-in programs and general platform maturity, AMD’s alternative lies elsewhere.
First, turning into the {industry}’s most credible second platform;
Second, leveraging its present enterprise CPU relationships;
Third, competing aggressively in inference, the place price, availability, energy effectivity and workload economics might matter greater than absolute peak efficiency;
Lastly, AMD’s dedication to open requirements provides it a messaging angle that can resonate with prospects in a market the place many enterprises have gotten more and more involved about dependence on a single provider.
So the underside line isn’t that AMD goes to overhaul Nvidia. It’s that AMD is steadily assembling the capabilities required to develop into the indispensable second platform for AI infrastructure – and in a market rising this shortly, that has been sufficient to create monumental worth; and there’s probably rather more to return.
What does profitable appear to be for AMD?
All the things we’ve mentioned results in this considerably apparent conclusion. AMD doesn’t have to beat Nvidia. In our view, that’s the mistaken method to consider it.
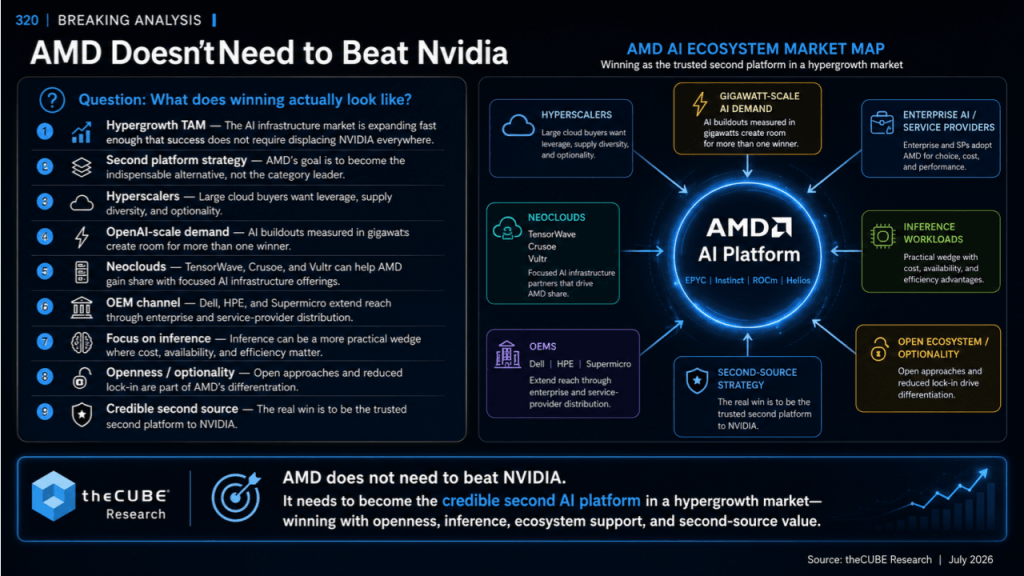
The AI infrastructure market is increasing so quickly that there’s room for a couple of profitable platform. Profitable doesn’t imply turning into the class chief. It means turning into the {industry}’s most trusted second platform.
The next factors summarize why:
Hyperscalers don’t like single-source dependence;
Enterprise prospects need negotiating leverage;
So do OEMs like Dell, HPE and Supermicro – plus they need selection of their portfolios; and
The quickly rising Neoclouds like Tensorwave are actively searching for differentiated infrastructure methods.
On the similar time, inference is turning into an more and more vital battleground – one the place entry economics, availability, energy effectivity and workload optimization can matter as a lot as peak benchmark efficiency. AMD’s dedication to openness, {industry} requirements and heterogeneous computing additionally provides prospects a substitute for extremely built-in proprietary platforms.
None of those benefits displace Nvidia. However collectively, they create a really credible path to turning into the popular second platform. And that’s why we imagine AMD’s alternative isn’t to develop into one other Nvidia. It’s to develop into indispensable to prospects who need selection, resilience, and suppleness in what’s quickly turning into the most important infrastructure market in computing historical past.
Evaluating financials of the AI silicon gamers
What would a Breaking Evaluation be with out some numbers? In the end, the funding case comes right down to the financials and the sturdiness of enterprise fashions.
The primary level is one we’ve emphasised all through this evaluation. AMD doesn’t have to displace Nvidia to create important shareholder worth. Buyers have rewarded AMD with a almost $1 trillion valuation as proven beneath ($800 billion-plus).
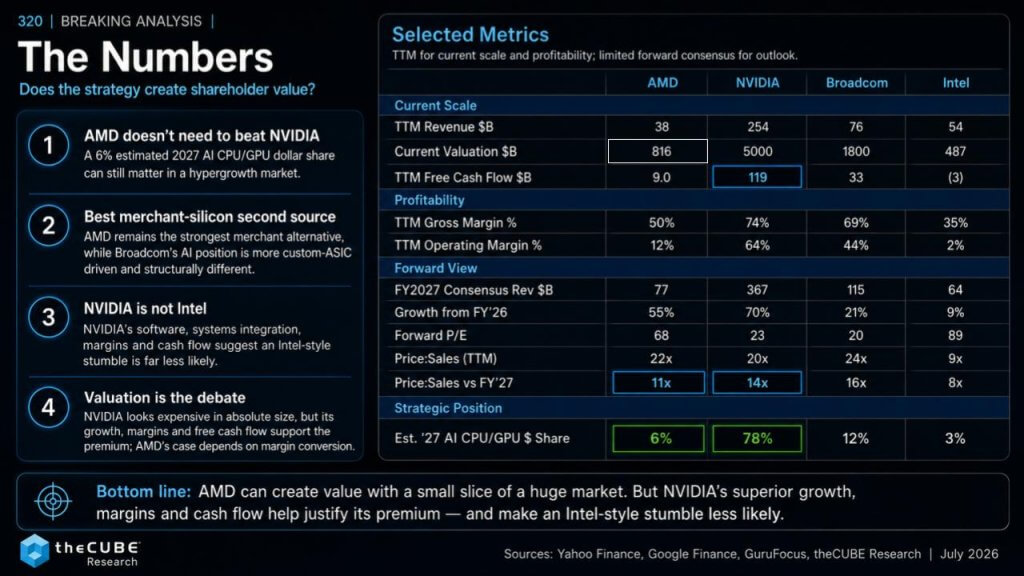
If the corporate captures even a mid-single-digit share of the AI accelerator market (we’ve got them above at 6%) whereas sustaining its CPU management, it might probably take part meaningfully in one of many fastest-growing infrastructure markets we’ve ever seen; and it’s valuation can have upside assuming execution and the bubble doesn’t burst within the close to time period.
Second, AMD stays the strongest merchant-silicon various. Broadcom is an distinctive firm, however its AI enterprise is primarily pushed by customized ASICs constructed for hyperscalers. Broadcom’s prospects construct full programs with Broadcom proving important IP. AMD is pursuing a broader service provider platform technique.
Third – and that is apparent however vital to emphasise – Nvidia isn’t a wounded Intel. Nvidia’s aggressive place is basically completely different. Its software program ecosystem, networking management, programs integration, margins and money technology make an Intel-style stumble far much less seemingly.
Lastly, valuation stays in focus.
Notably, AMD trades at valuation multiples that assume important future AI success, whereas Nvidia’s extraordinary profitability and money flows counsel it could be comparatively undervalued. Nvidia’s development charge is way larger than any competitor. It’s margins are higher, its free money move is much larger. The corporate has no debt. But its ahead price-to-earnings ratio is about the identical because the S&P 500 regardless of it rising at 5 instances the collective development charge of the businesses in that index.
Our conclusion is fairly clear, nevertheless. AMD has created and may proceed to create substantial worth with a comparatively small slice of a really massive market. Buyers ought to on the similar time acknowledge that Nvidia’s management in the present day is actual – and we expect sustainable – which is exactly why AMD’s technique is centered on turning into the popular second platform moderately than making an attempt to disrupt the market chief the identical method it did Intel.
The technique is ready – it’s now all about execution
In the end, the success of AMD’s technique comes right down to execution. The excellent news is that execution has develop into one in every of Lisa Su’s biggest strengths. Over the previous decade, AMD has persistently delivered on formidable roadmaps, regained credibility with prospects and buyers, and constructed one of many strongest engineering cultures within the semiconductor {industry}.
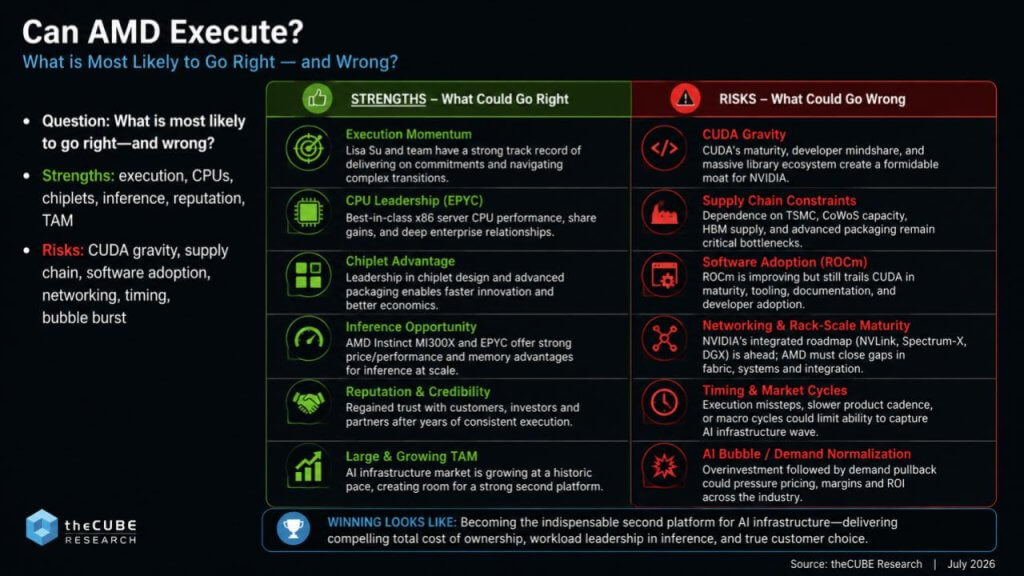
That provides us confidence that the corporate can proceed closing the gaps relative to the chief – not less than to the purpose the place it would promote each AI system it might probably construct. However buyers also needs to acknowledge that the challenges are substantial. CUDA stays one of many strongest software program moats in know-how. Provide-chain constraints – from high-bandwidth reminiscence to superior packaging to vitality to knowledge heart builders – will proceed to control the tempo of the buildout. Particularly as a giant hope for AMD rests on its OpenAI deal to construct out six gigawatts of capability in 4 to 5 years.
ROCm is bettering quickly, but it surely nonetheless trails CUDA in ecosystem maturity and developer adoption. And Nvidia continues to increase its lead in networking, rack-scale programs, and built-in AI infrastructure.
Lastly, timing as they are saying, is all the pieces. AI infrastructure spending is rising at a rare tempo in the present day, however know-how cycles are by no means linear. Slower execution, modifications in buyer demand, or a normalization in AI funding may all have an effect on AMD’s trajectory. All that mentioned, general, we imagine AMD’s strengths far outweigh its dangers and it’s properly positioned in a fully monumental market.
Success gained’t appear to be AMD turning into one other Nvidia. It will likely be measured by executing properly sufficient to develop into the popular various for AI infrastructure, delivering compelling economics, prime quality inference, real buyer selection and constant execution.
Abstract and motion merchandise for AI operators
Let’s shut the place we started.
AMD’s first reinvention was a comeback story. It rebuilt the corporate by beating Intel in a mature x86 market by way of higher structure, higher execution, and disciplined management. Its subsequent reinvention is basically completely different. This isn’t a battle to interchange and even beat Nvidia. It’s a race to develop into the indispensable second platform for AI infrastructure.
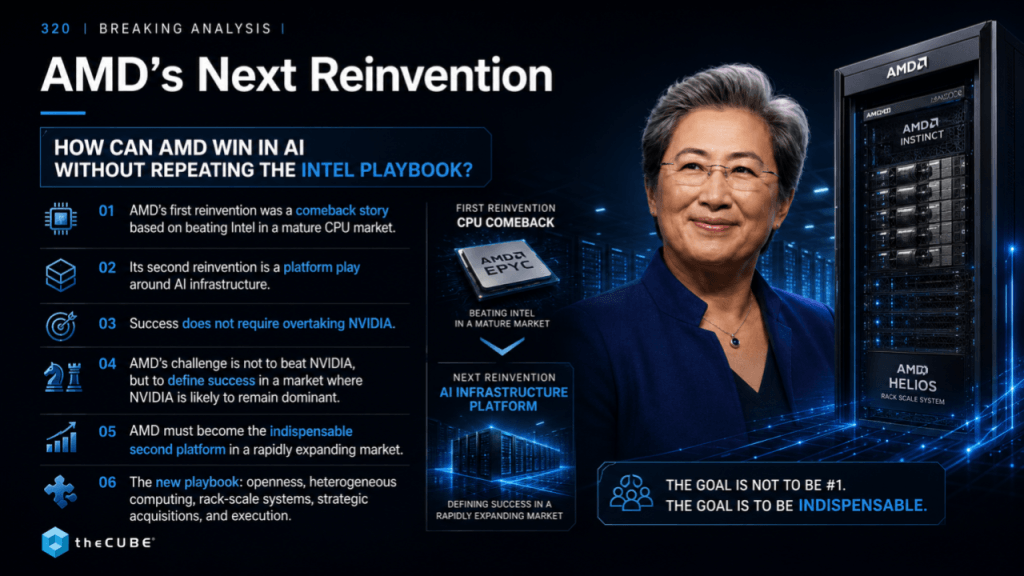
If Lisa Su and her staff can efficiently combine EPYC, Intuition, ROCm, networking, rack-scale programs and the broader software program ecosystem right into a coherent platform, AMD doesn’t must develop into the market chief to ship outsized returns. It has to develop into the trusted various that each enterprise, hyperscaler, OEM and neocloud believes they need to have of their AI technique to shut provide/demand gaps, maintain Nvidia sincere and fill seams out there.
In a market anticipated to create trillions of {dollars} of recent infrastructure spending over the approaching decade, which may be probably the most priceless positions in know-how.
So right here’s our Breaking Evaluation Motion Merchandise.
Should you’re chargeable for AI infrastructure technique – whether or not you’re an information heart operator, AI architect, platform engineering chief, or CIO – don’t wait till you want a second platform. Qualify one now. Benchmark AMD on actual workloads. Validate the software program stack. Perceive the place EPYC, Intuition and Helios suit your structure.
Not as a result of we imagine Nvidia goes away or is underneath hearth.
Fairly the other.
Preserving strategic optionality in the present day creates negotiating leverage, operational resilience and architectural flexibility tomorrow. In our opinion, that’s the true lesson from AMD’s subsequent reinvention. The mandate isn’t to interchange Nvidia in every single place. It’s to construct strategic optionality by qualifying AMD the place it creates leverage, resilience and financial benefit.
Picture: theCUBE Analysis
Disclaimer: All statements made concerning corporations or securities are strictly beliefs, factors of view and opinions held by SiliconANGLE Media, Enterprise Know-how Analysis, different friends on theCUBE and visitor writers. Such statements will not be suggestions by these people to purchase, promote or maintain any safety. The content material introduced doesn’t represent funding recommendation and shouldn’t be used as the idea for any funding resolution. You and solely you’re chargeable for your funding selections.
Assist our mission to maintain content material open and free by partaking with theCUBE neighborhood. Be part of theCUBE’s Alumni Belief Community, the place know-how leaders join, share intelligence and create alternatives.
15M+ viewers of theCUBE movies, powering conversations throughout AI, cloud, cybersecurity and extra
11.4k+ theCUBE alumni — Join with greater than 11,400 tech and enterprise leaders shaping the long run by way of a singular trusted-based community.
About SiliconANGLE Media
Based by tech visionaries John Furrier and Dave Vellante, SiliconANGLE Media has constructed a dynamic ecosystem of industry-leading digital media manufacturers that attain 15+ million elite tech professionals. Our new proprietary theCUBE AI Video Cloud is breaking floor in viewers interplay, leveraging theCUBEai.com neural community to assist know-how corporations make data-driven selections and keep on the forefront of {industry} conversations.

