


By Arvind Narayanan and Akash Kapur
Our purpose on this essay is to maneuver past the talk over whether or not AI is a bubble. We accomplish that in two methods: clearly separating present financials from the query of who captures worth in the long term, and recognizing that the labs are usually not confined to be mannequin suppliers. They’ll migrate up the stack and are already aggressively doing so. This can seemingly enable them to flee the commodity lure however raises new considerations — buyer lock-in and decreased competitors.
Akash Kapur is a visiting fellow at Princeton and a senior fellow at New America. He’s no relation to Sayash Kapoor.
As main AI corporations proceed to speculate massively in capability and race towards blockbuster IPOs, severe questions linger about their enterprise fashions. How will these corporations — together with the huge ecosystem of chipmakers, hyperscalers, and infrastructure companions that relies on them — recoup the estimated $4–8 trillion projected to be invested in AI infrastructure by the early 2030s?
The present dialog splits between critics and boosters. Critics level to mounting losses, the hole between capex and income, and experiences in regards to the main labs’ huge money burn. Boosters cite accelerating fast income development, enterprise adoption, and milestones like Anthropic’s first worthwhile quarter. Every camp has a legitimate level. However each are trying within the incorrect place — the identical quarterly statements, the identical short-term view of an business that continues to be in flux.
In current months, now we have been serious about the character and sustainability of the AI enterprise, and we’ve landed in a special place than a lot of the present commentary. AI corporations in the present day earn a lot of their income by charging for inference, however the circumstances of frontier inference make this an unusually troublesome enterprise to keep up. Fashions are largely undifferentiated, the main labs function with related capital buildings, switching prices are low, and costs may be adjusted freely. All of this seems to arrange the circumstances for a commodity lure that will pose actual challenges to the duty of constructing high-margin and even worthwhile companies.
On the similar time, we imagine that the business stays in a transitional stage, and that its construction will look very completely different when it matures. Drawing on each historic proof and financial principle, we argue that competitors on this equilibrium is more likely to push the worth of mannequin inference towards the marginal price of manufacturing tokens, leaving little room for sturdy earnings on the mannequin layer. This doesn’t imply, nevertheless, that the enterprise of AI is inherently unviable. The identical evaluation suggests a path ahead for AI labs, and results in the central argument of our paper:
The labs’ probably path to sturdy profitability runs not by means of the muse layers (chips, datacenters, fashions) which have to date accounted for the majority of investments, however larger up the stack, by means of a mixture of vertical integration, embedded enterprise deployments, and the deliberate building of switching prices and different “moats”.
The labs’ methods to seize worth by transferring up the stack, many borrowed from the playbook of enterprise software program, have already begun. Past the sustainability of the present AI ecosystem, they elevate questions of broader societal concern — about competitors, innovation, and the general distribution of financial and political energy. The general public dialogue over AI to date has been marked by a considerably paradoxical dichotomy: anxiousness about monopolistic focus and runaway market energy, but a actuality of low switching prices and comparatively interchangeable fashions that appears to belie these fears. But when we’re proper that the labs will more and more transfer larger up the stack, then considerations about focus and competitors are value taking critically now, somewhat than after the results of lock-in begin to materialize. We return to those broader points within the conclusion — and in a forthcoming paper that dives deeper into lots of the matters lined on this publish.
The AI as Regular Know-how framework is dedicated to drawing classes, when relevant, from previous transformative applied sciences. We expect AI is topic to lots of the similar dynamics associated to funding, competitors, and worth seize which have formed earlier waves of technological innovation. As a part of our analysis, we subsequently examined the puzzle of AI worth seize, and the labs’ seemingly response to it, by means of a broader historic lens.
We checked out six historic situations of capital-intensive infrastructure industries (railroads, electrical energy, telecom and fiber, cloud computing, semiconductor manufacturing, and industrial aviation). We imagine that AI in the present day has many infrastructure-like traits: huge capital necessities; low marginal price; a commodity product that’s considerably decoupled from the functions that finally create worth. This makes infrastructure a notoriously robust enterprise to be in.
However on the similar time, AI is software program, and the software program enterprise has traditionally been profitable, with exceptionally excessive margins. The business has software-margin ambitions. Thus, we additionally surveyed the value-add and lock-in methods of software-as-a-service, and analyzed whether or not AI can replicate these. Our thesis is that AI corporations’ sustainability and value-capture largely activates how efficiently they will migrate from the primary set of infrastructural properties towards the second enterprise-software ones.
Broadly, we recognized three instructive classes for AI from our historic evaluation. First, infrastructure suppliers not often seize the worth they create. Throughout railroads, electrical energy, telecom, and airways, the corporations that constructed capability had been finally competed, regulated, or commoditized into skinny margins. In lots of instances, they had been destroyed outright. In the course of the telecom and fiber buildout of the late Nineties, capability exploded 186,000-fold in seven years, costs crashed, and roughly $2 trillion in market capitalization was erased. The worth generated by the infrastructure primarily accrued to industries and functions constructed on high of it. Business aviation has destroyed investor capital for eight many years, as a result of typical web margins are 2–4%, typically under the price of capital — at the same time as companies of all stripes benefited from a globalized economic system.
We imagine that AI, a minimum of in its present hyperscaler kind, dangers falling into the identical commodity lure that has bedeviled so many earlier infrastructure builders. Carlota Perez has theorized the paradoxical phenomenon that the builders who create infrastructure throughout the “set up interval” not often survive to seize the worth it creates.
Second, enterprise software program shouldn’t be topic to this sample, and it escapes the lure by means of a particular and reproducible set of mechanisms. The place infrastructure corporations have struggled, enterprise software program has sustained gross margins of 75% or extra for many years. It does so by combining three properties that infrastructure companies lack: zero marginal price of copy, deep switching prices, and non-ephemeral worth that enables fastened buildout prices to be amortized over many years. The AI labs’ lock-in methods are finest understood as makes an attempt to import these structural properties of software program into AI.
Lastly, two partial exceptions reveal what it might take for AI to beat the historic odds. Two infrastructure companies — cloud computing and chip fabrication — have managed to flee the commodity lure. Cloud acquired software-like properties (managed-services lock-in, egress charges, committed-spend agreements) and TSMC achieved a near-monopoly place in modern fabrication. These instances matter as a result of they present what escape from the commodity lure really requires. Capital-intensive industries can maintain sturdy margins, however solely by both changing into functionally software program or reaching market focus.
As famous, critics of the AI buildout level to the labs’ present losses and boosters to early earnings, however each are committing the identical error: mistaking the transitional interval for the equilibrium. We’re nonetheless within the early years of the AI transformation of the economic system, and naive extrapolation is flawed. In equilibrium, each the availability and demand aspect will look very completely different than they do in the present day.
A number of examples of the fluctuating fortunes of the AI labs to date: An enormous and speculative infrastructure buildout that was arguably forward of demand; the Deepseek second throughout which open-weight fashions virtually caught as much as the frontier; a surge in demand as corporations embraced AI brokers, typically accompanied by irrational and wasteful practices corresponding to token leaderboards, resulting in a so-called period of token shortage; and, most just lately, a renewed push for a aggressive open-source ecosystem as corporations rethink their spending on frontier fashions.
These ups and downs have many parallels within the historic case research talked about above. The railways at first noticed a speculative frenzy (the railway mania of the 1840s in Britain). In America, over time, demand exceeded capability, leading to estimated direct and oblique returns of 15% every year on railroad capital by means of 1860 — monumental for the period. However because the community matured, capability caught as much as demand, competitors squeezed margins, and plenty of railroad corporations went bankrupt.
Thus, to higher forecast the labs’ long-term prospects, it’s useful to step again from the year-to-year and quarter-to-quarter swings in financials (and narratives), and floor our evaluation in financial principle. A key idea is the Bertrand paradox: this says that when corporations promote a homogeneous product (frontier-model inference), value competitors will pressure them to promote every unit (token) on the marginal price of manufacturing it.
The theoretical evaluation is essential as a result of the query of how properly the historic report predicts the AI business’s fortunes is contested. For instance, our colleague Mihir Kshirsagar identifies regulation as the principle purpose why railroad, electrical and telecom corporations had been unable to extract the excess generated by their infrastructure, somewhat than viewing it as an inherent consequence of their economics. Thus, the idea provides us a further purpose to anticipate a margin squeeze. Though the theoretical paradox is straightforward to flee in apply, we imagine that mannequin inference accommodates an unusually pure model of the circumstances that produce the paradox:
Fashions are largely undifferentiated. No less than three corporations, OpenAI, Anthropic, and Google have managed to remain on the frontier and produce fashions that behave and carry out equally to one another. In addition to, for an rising fraction of use instances, frontier efficiency shouldn’t be mandatory, and open-weight fashions are ok. Moreover, the near-equivalence of fashions is quickly noticed or perceived by prospects, as a result of there are a whole bunch of benchmarks on which fashions are repeatedly evaluated and frontier fashions all are inclined to cluster close to the highest.
For a revealing distinction from one other business, Apple famously sustains excessive margins by escaping this facet of Bertrand competitors. It resists competing on objectively observable dimensions of efficiency (gigahertz, megapixels), as an alternative promoting outcomes and ineffable qualities (“it simply works”) and creates sturdy model differentiation.
The distributors all have related capital prices. AI information diffuses quickly; the foremost paradigms of mannequin improvement — mannequin scaling, inference scaling, reinforcement studying, and so forth — have all proceeded in near-lockstep. So to provide a token at a given output high quality, the labs all spend related quantities on coaching. In a hypothetical future the place the frontier doesn’t transfer as quickly, prices will likely be dominated by inference, and inference price tends to be much more related than coaching price.
Lack of geographic differentiation. Within the case of the railroads, a patchwork of native monopolies, and captive capability, supplied some protection towards margin compression. The enterprise of AI inference lacks this differentiation, and corporations can successfully serve the total market. Whereas there’s arguably a token capability constraint in the present day, we anticipate this to be non permanent.
Costs may be modified freely, with no collusion. Railroads and utilities had been capable of collude tacitly or explicitly to maintain costs excessive at some factors of their historical past. However that is extremely unlikely with AI fashions as a result of there’s fierce competitors from sub-frontier fashions.
Switching prices are minimal. Even the friction of migrating APIs is basically eradicated by a layer of provider-agnostic routing instruments.
One potential response to all that is to argue that it doesn’t matter how a lot margins get squeezed, as a result of AI corporations will merely make it up in quantity. However the numbers don’t work out. If we assume a 5% web margin — a lot larger than airways — and the necessity to recoup the aforementioned $4T — $8T of funding over a 5-year horizon, we find yourself with a requirement of $16 – $32T in annual income, the upper finish of which is 1 / 4 of in the present day’s world GDP.
Taking this longer-term perspective, grounded in historical past and financial principle, permits us to disregard a number of elements that different analysts are inclined to critically index on. For now, we’re in a interval through which huge, capital-intensive coaching runs proceed to provide higher fashions. This forces labs to remain on an improve treadmill through which they reinvest their revenues into coaching (after which some) taking up ever-higher investments. When this treadmill slows, the enterprise will attain a brand new stage of equilibrium that’s more likely to look very completely different from in the present day. In that state, three elements that presently dominate the talk will matter far lower than they seem to now.
The primary is falling token costs pushed by effectivity enhancements, which critics cite as proof of a race to the underside that can shrink the dimensions of the pie. In our view, whereas it’s true that token costs have been falling quickly (and that this pattern will seemingly proceed), it isn’t essentially an issue for the labs. Relying on the form of the demand curve, unlocking demand might greater than compensate for falling costs — the so-called Jevons’ paradox, through which effectivity beneficial properties result in better (not much less) consumption of a useful resource.
The second is token shortage, which boosters cite as proof of the labs’ pricing energy. Any shortage, nevertheless, is probably going a short lived phenomenon that will likely be alleviated or eradicated by a mixture of infrastructure funding and algorithmic enhancements. Token shortage is subsequently unlikely to permit the labs to extend their margins.
The third issue that dominates the present discourse is willingness to pay. Critics typically predict that demand will evaporate when labs finish their sponsored, below-cost subscription pricing. However this treats willingness to pay as a set amount, one thing that may be extrapolated ahead from in the present day. Over the long term, we anticipate that AI will likely be a necessary a part of most information work, and that the expertise will likely be as transformative as the commercial revolution. In a transition of this scale, the willingness to pay is doubtlessly monumental.
In different phrases, we should distinguish between worth creation and worth seize. We anticipate the worth created to be unfathomably massive. The central — maybe even existential — query for the labs is whether or not they are going to be capable of seize even a small proportion of that worth. What fraction of the worth AI creates for an organization will that firm be prepared to pay the AI distributors? This isn’t some free-floating, exogenously decided quantity. It’s largely decided by the extent to which AI labs are capable of escape the commodity lure.
As we argue under, essentially the most dependable strategy to escape the commodity lure is to maneuver downstream within the financial worth chain (within the case of AI, this implies transferring “up the stack”). Transitioning from promoting bodily infrastructure or merchandise to bundles that embrace providers is usually referred to as “servitization”. For instance, as {hardware} turned commoditized, IBM efficiently transitioned to a providers firm, finally promoting its PC division altogether to Lenovo. The telecom corporations additionally made sustained, strenuous efforts to keep away from changing into “dumb pipes”, however unsuccessfully. Worth was as an alternative captured by functions that utilized the infrastructure, resulting in the rise of Massive Tech. We imagine that labs now face a lot the identical fork: seize worth within the layers above the fashions, or watch others create profitable companies on high of the infrastructure they constructed and paid for.
To summarize our argument to date, our historic evaluation in addition to financial principle means that there exist solely two believable routes out of the commodity lure: establishing monopoly-like management over the market, or capturing worth at larger layers of the stack, typically accompanied by elevated switching prices.
We imagine that the primary route is unlikely and the frontier will keep aggressive. Proponents of AI exceptionalism would possibly disagree, forecasting a improvement with out historic precedent: a functionality discontinuity so dramatic that it reshapes the aggressive panorama totally. On this “laborious takeoff” situation, a number of labs achieves recursive self-improvement, rendering the present economics largely irrelevant.
In our full paper, we argue why this situation is extremely implausible. For now, we level out that many policymakers, buyers, and different stakeholders are usually not comfy betting on such a chance, and should as an alternative plan for a situation the place it doesn’t pan out.
This leaves transferring up the stack because the probably path ahead. We imagine AI corporations are properly conscious of the commodity lure; they’re full-throatedly transitioning past being pure inference distributors (i.e., promoting undifferentiated tokens by means of mannequin APIs), and in search of to pursue worth seize at larger layers of the stack. We’re within the early days of those efforts and plenty of new and extra systematic methods are more likely to emerge (we look at some within the subsequent part). However already, some efforts are obvious.
Merchandise like ChatGPT or Claude Code sit at a layer above fashions. Merchandise are usually not interchangeable in the way in which fashions are, for a bunch of technical, contractual, and behavioral causes, as we talk about within the following part. In OpenAI’s case, ChatGPT, not the OpenAI API, has lengthy accounted for almost all of its revenues. Anthropic’s revenues in early 2026 had been nonetheless dominated by its API, however with the explosive development of Claude Code, that may not final for for much longer.
The subsequent layer within the stack is AI-native SaaS or “intelligence as a service”, and the labs have made early strikes on this route: ChatGPT’s firm information function, and Anthropic’s imaginative and prescient of brokers contained in the System of Report. Nevertheless, that is the layer the place the labs are most susceptible to present SaaS incumbents, notably Microsoft.
AI corporations are additionally pursuing bespoke deployment and workflow redesign — by means of forward-deployed engineers and partnerships with consulting corporations. This doesn’t match cleanly into the stack. The stack assumes an equilibrium through which workplaces have been remodeled by means of AI, whereas this class is about trying to monetize the transformation itself.
Probably the most speculative, and extra doubtlessly profitable, avenue for worth seize is the highest layer of the stack: the thought of AI brokers as “digital employees”. Many corporations have been touting this thought. Maybe the primary launch from a significant AI firm that has been designed to perform analogously to a digital employee somewhat than a instrument is Claude Tag, launched in June 2026. A digital employee that’s embedded with each workforce in an organization shortly turns into a retailer of tacit information for the entire group and turns into important to workflows and enterprise processes throughout completely different groups. Except portability is explicitly inbuilt, it turns into a digital worker that successfully can’t be fired, making a degree of lock-in that exceeds that of enterprise software program at its worst. When corporations promote digital employees, the entire addressable market is the economic system’s total labor spend, far bigger than corporations’ IT budgets. However exactly for these causes, the imaginative and prescient is more likely to encounter essentially the most resistance from enterprises.
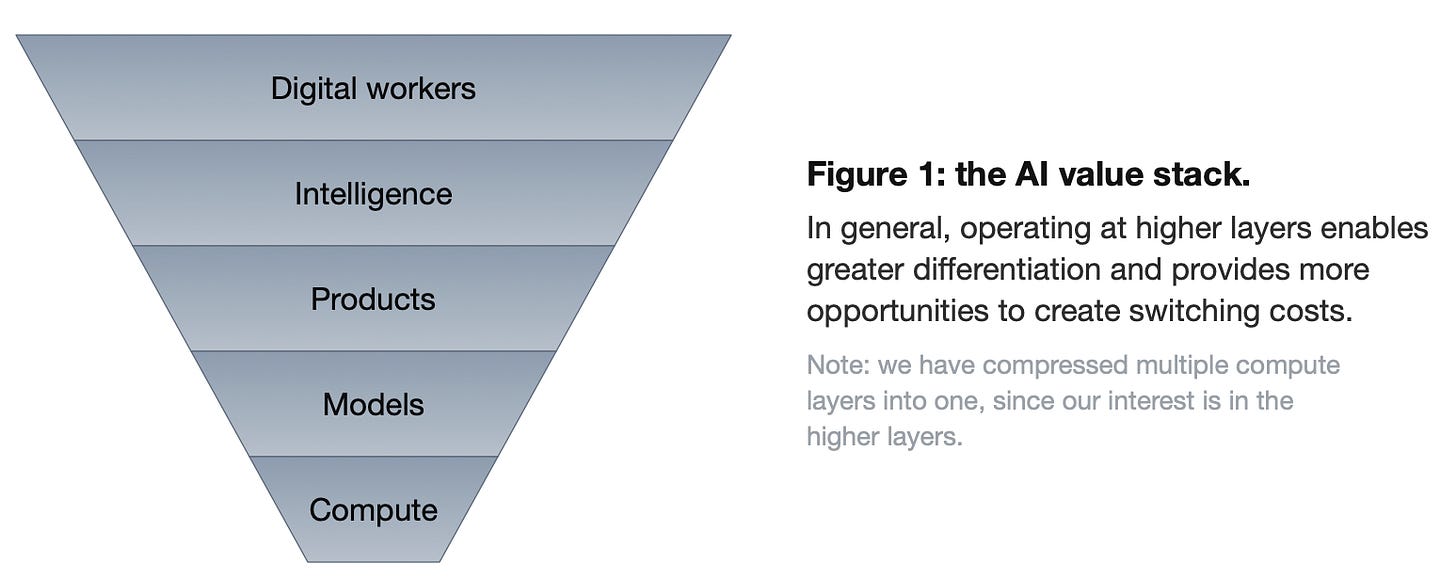
Determine 1 illustrates a few of these ongoing efforts. Notice that the stack describes what the client pays for, not the billing unit. Token pricing can be utilized at any layer of the stack, and different models (subscriptions, outcomes) can be utilized together or as substitutes on the larger layers. It’s the kind of worth at every layer of the stack that determines whether or not the commodity lure applies, not the pricing mannequin. We talk about pricing methods in additional element within the following part.
A key perception of this essay is that corporations that function larger on this stack can seize extra of the worth that they create. They’ll higher differentiate their choices and construct a wide range of moats (as we talk about under), lots of that are arguably novel and extra highly effective than enterprise software program loved.
An essential caveat: for AI labs, particularly OpenAI and Anthropic, to maneuver up the stack, they need to compete with bigger incumbents who take pleasure in many benefits, notably present distribution channels and deep enterprise buyer relationships. Google enjoys straightforward vertical integration into its present shopper product line. SaaS incumbents, notably Microsoft, are betting that they will crack the “intelligence as a service” mannequin sooner than the AI labs can. This unevenness reshapes the aggressive dynamics of the AI ecosystem, and factors to essential variations among the many key gamers trying to climb the worth stack.
How does transferring up the stack enable corporations to flee the commodity lure? The reply shouldn’t be merely that larger layers create extra financial worth. It’s that they make worth capturable and sturdy: working larger within the stack permits labs to tell apart their choices and to assemble lock-in and switching prices of a sort unavailable to sellers of uncooked inference, that’s, API suppliers. They successfully enable AI corporations to flee the shortage of differentiation that lies on the coronary heart of the Bertrand paradox. Strikes up the stack are usually not simply new product methods; they’re moat-building methods. On this part, we look at a number of completely different sorts of moats—some that labs are already constructing, and a few that they could construct sooner or later.
To determine what moats open up as AI corporations transfer up from the mannequin layer, we checked out how enterprise software program corporations generate pricing energy and seize worth, then analyzed which of these methods are seemingly relevant to AI corporations and what new ones change into out there.
We be aware two essential nuances earlier than we dive in. First, whereas moats are methods to defend market share from opponents, our curiosity is in analyzing AI corporations’ skill to seize the worth that they create for prospects. Nonetheless, the methods concerned are largely the identical, as a result of each require avoiding a pricing race to the underside.
Second, our evaluation focuses on the enterprise market, since we imagine that it’ll account for the majority of revenues. OpenAI has pivoted on this route just lately whereas Anthropic has had a constant concentrate on enterprise. Whereas it’s potential that ad-driven shopper merchandise could possibly be a big income stream sooner or later, thereby taking part in a task in escaping the commodity lure, that doesn’t undermine our thesis about enterprise moats.
1. Embedding moats: AI fashions are one thing that prospects invoke of their workflows. However one other imaginative and prescient of AI is a system that the client inhabits. The latter is extra conducive to constructing moats.
Even when the underlying mannequin stays interchangeable, the state wrapped round it for a given buyer is probably not. Over time, that state accumulates: persistent reminiscence and dialog historical past, uploaded doc corpora and retrieval indexes, customized expertise or analysis suites, workflows and enterprise processes, and varied types of fine-tuning or customization. This “information gravity” is an enormous a part of what provides enterprise software program its stickiness, and why changing it has been described as “open-heart surgical procedure”.
Each OpenAI (Firm Data) and Anthropic (Claude Cowork, the PwC partnership) are already pursuing these pathways. The sturdiness of those methods stays an open query. One complication is that the information that would assist construct moats usually sits on corporations’ servers in established techniques like Salesforce, Workday, and SAP, largely inaccessible to AI labs. To beat this, AI corporations might construct moats by controlling the orchestration layers occupied by brokers, thus successfully offering the connective tissue that binds a corporation’s workflows. Nevertheless, if open requirements preserve the orchestration layer skinny and swappable, worth might finally stream to agentic integrators and enterprises somewhat than the labs themselves.
2. Ecosystem moats: Enterprise software program corresponding to Home windows, GitHub, and SAP all benefited from the truth that, as they gained extra prospects or builders that constructed on high of the platform, the worth of the platform grew. The AI market doesn’t but exhibit sturdy ecosystem moats. Labs have made efforts to create two-sided marketplaces on high of AI as a platform, however to date these have both been unsuccessful (GPT retailer) or too skinny to create significant switching prices (Claude plugins).
A much-discussed however as-yet-unrealized form of community impact is the “flywheel” of coaching AI fashions or techniques utilizing prospects’ IP, whether or not information, the environments through which brokers execute, the execution traces of these brokers, or personal analysis suites. To date, enterprises have been skittish about permitting their IP for use this fashion by AI builders, however this may increasingly change sooner or later. In spite of everything, it takes just one (suitably incentivized) buyer in every sector to defect to set a flywheel into movement.
3. Business moats: This class covers a variety of acquainted methods, largely borrowed from enterprise software program and cloud computing. Business contracts can embrace varied mechanisms (multi-year agreements, committed-spend tiers, pay as you go credit) that make defection to rivals uneconomic. The labs are already deploying a few of these mechanisms of their enterprise agreements, however the sturdiness of this moat can also be questionable. Subtle enterprise procurement groups will demand portability earlier than signing, and contractual lock-in is extremely legible to antitrust regulators.
Vertical integration presents a extra highly effective model of the identical industrial logic. When an AI assistant is bundled into software program an enterprise already pays for (Copilot inside Microsoft 365, Gemini inside Google Workspace) the marginal price of AI seems to be zero, making it troublesome for standalone opponents to compete on value. Built-in gamers may also journey present gross sales and procurement relationships: as an alternative of successful a brand new funds line, they merely fold AI right into a renewal dialog for software program the client is already dedicated to. In fact, this technique is just out there to built-in incumbents like Google and Microsoft. As famous above, which means that standalone labs like OpenAI or Anthropic should compete on a structurally uneven taking part in subject, typically renting infrastructure from the very corporations they’re up towards.
4. Behavioral moats: Whereas the moats mentioned above function by means of technical or industrial mechanisms, behavioral moats work by means of the people who use AI techniques. Very like earlier waves of enterprise software program (Microsoft Excel, CRM techniques), using AI instruments can result in an erosion of the talent at performing duties unaided, whereas on the similar time constructing vendor-specific expertise in driving agentic merchandise, creating dependence. That is an space the place the societal stakes could also be acute, past its implications for worth seize: talent erosion might have profound implications for workforce resilience, security, and the distribution of energy between individuals and AI techniques.
However behavioral moats additionally embrace novel and poorly understood types of AI lock-in that haven’t any clear analog in earlier software program. A notable manifestation is relational attachment to a mannequin’s tone or “persona,” as vividly demonstrated by the #Keep4o backlash, when OpenAI was pressured to reinstate GPT-4o in response to person calls for. Extra speculatively, for collaborative information work corresponding to writing or judgment-heavy work (versus automation), the standard of AI’s contribution is difficult for the client to confirm even after the very fact, as a result of there aren’t any goal requirements. That makes such work a so-called credence good, just like legal professionals and consultants. Unable to check high quality, patrons of credence items are inclined to depend on repute and belief. This mutes value competitors and slows switching even when the technical price of switching is near zero.
5. Pricing methods: This pathway is complementary or additive to those mentioned above, and describes a means through which labs would possibly be capable of seize extra worth after they obtain lock-in and are capable of exert pricing energy. The thought is that labs could possibly overcome the commodity lure by charging for outcomes (a proportion of price saved, a charge per resolved assist ticket) somewhat than tokens. That is the specific thesis behind OpenAI CFO Sarah Friar’s assertion that income ought to “scale with the worth of intelligence.”
Nevertheless, that is unlikely within the quick time period. Consequence pricing requires fixing a difficult measurement downside. The labs haven’t constructed the infrastructure to measure and perceive prospects’ enterprise processes, and to trace — not to mention value — completely different outcomes. With out that visibility, final result metrics invite gaming by either side: a charge per resolved ticket incentivizes prospects to stuff a number of points into one ticket and distributors to shut tickets with out essentially fixing them. In addition to, outcomes fluctuate between verticals and between corporations, and AI labs lack the embedded buyer groups that SaaS distributors spent many years constructing so as to acquire this type of downstream visibility. Nonetheless, some AI corporations are attempting to innovate on this entrance. If AI labs are capable of migrate into Methods of Report, the challenges change into tractable with sufficient funding.
The questions raised by our evaluation have a big bearing on the way forward for the AI economic system, however they lengthen properly past the prospects of any particular person AI firm. They contact on the construction of digital markets, the distribution of financial energy, and the form of innovation ecosystem that AI is more likely to produce.
If the labs fail to flee the commodity lure, the results are primarily monetary: a possible disaster of confidence in one of many largest capital buildouts in financial historical past, with ripple results by means of the broader expertise sector and markets usually. But when they succeed — significantly in the event that they handle to extend switching prices and set up buyer lock-in — the results look completely different, and in some methods extra regarding. It could elevate prices for each enterprise that relies on AI and entrench a small variety of gamers ready of structural benefit that will likely be troublesome to contest later.
A number of questions particularly appear value taking critically now, earlier than the related moats have hardened:
Can the labs construct sustainable companies with out foreclosing competitors and repeating earlier patterns of dangerous focus?
Can methods that work for buyers and AI corporations additionally generate wider social worth, or does worth seize in AI come on the expense of the encompassing ecosystem?
Will the beneficial properties from AI be diffuse (accruing primarily to the enterprises that deploy it, and the broader economic system) or concentrated (largely captured by hyperscalers, frontier AI labs, SaaS incumbents, and buyers)?
There stays a lot uncertainty about these questions, however historical past means that the time to ascertain interoperability requirements, portability necessities, and switching-cost transparency is early, earlier than lock-in compounds and intervention turns into structurally harder. Happily, competitors authorities such because the U.S. FTC and the UK CMA are watching this area, however to date they seem to have centered their evaluation on the underside layers of the stack. Our evaluation exhibits that they need to broaden their view.
We’re grateful to Sayash Kapoor for suggestions on a draft.
Whereas many features of our argument are a minimum of considerably novel, the “no moat” argument itself shouldn’t be new. Its first outstanding articulation (that we all know of) goes again over three years, in a leaked Google doc. Many commentators corresponding to Gary Marcus, Ed Zitron, and Cory Doctorow have relentlessly made this level or variants of it.
What’s probably new in our evaluation is drawing from historic parallels and exhibiting that mannequin inference matches the conditions for ruinous competitors even higher than these precedents do. The place we positively differ from these predicting a bubble is recognizing that (1) the AI stack is sort of thick and the commodity lure solely applies on the mannequin layer (2) the labs are keenly conscious of the issue and (3) have been furiously migrating their means out of it.
Many others are bearish on the labs, together with Benedikt Evans and Luis Garicano and Jesús Saa-Requejo. The latter argue that Worth seize will happen each on the high of the worth chain, the {hardware} and bodily suppliers [because of the compute bottleneck], and within the implementation layer, the place fashions are put to work and the place the binding constraint is organizational, not technical. We largely agree. However they conclude that the labs received’t be capable of seize a lot worth. The implicit assumption appears to be that the labs are confined to being mannequin distributors, which in our view is an more and more outdated notion.
Semianalysis argues that the labs will be capable of maintain excessive gross margins due to compute shortage. We expect this can be a non permanent state of affairs.
Closest to our pondering is our Princeton CITP colleague Mihir Kshirsagar, who has written a collection of 4 articles on this matter. Whereas now we have benefited from conversations with Kshirsagar, our pondering developed largely independently, with many factors of settlement and a few factors of disagreement. Like Kshirsagar, we predict the fast AI buildout doesn’t make financial sense if it weren’t for the promise of lock-in. His evaluation identifies coalitions between hyperscalers and AI labs (corresponding to Microsoft-OpenAI and Amazon-Anthropic) as the first automobile for lock-in, which is barely completely different from our prognosis.
Nathan Lambert presents one imaginative and prescient for the way this would possibly all play out — a two-tier AI economic system through which prospects who’re themselves on the frontier of data work pay large premiums for “up the stack” services based mostly on frontier fashions from the main labs, whereas everybody else is glad with the open mannequin ecosystem. One among his predictions is sharper than ours: frontier labs will let their API companies decay so as to defend their higher-margin choices.

