


Doubtlessly taxable onchain crypto exercise reached no less than $457 billion globally in 2025, whereas worldwide reporting guidelines might seize solely a fraction of it, in accordance with a brand new Chainalysis report.
The US accounted for an estimated $112.6 billion of the whole, whereas North America led all areas with $134.6 billion, adopted by the European Union at $125.1 billion.
The estimates embody realized good points, revenue from actions corresponding to mining, staking and lending, and crypto-denominated funds throughout six main blockchains, however exclude buying and selling and different exercise carried out inside centralized exchanges.
Chainalysis stated transactions coated by the Organisation for Financial Co-operation and Improvement’s (OECD) Crypto-Asset Reporting Framework (CARF) account for simply 14% of the onchain taxable exercise it recognized. The remaining 86% contains exercise on decentralized exchanges, peer-to-peer transfers, onchain revenue streams and funds.
CARF, developed by the OECD in 2022, requires coated crypto service suppliers to report buyer transaction information to tax authorities.
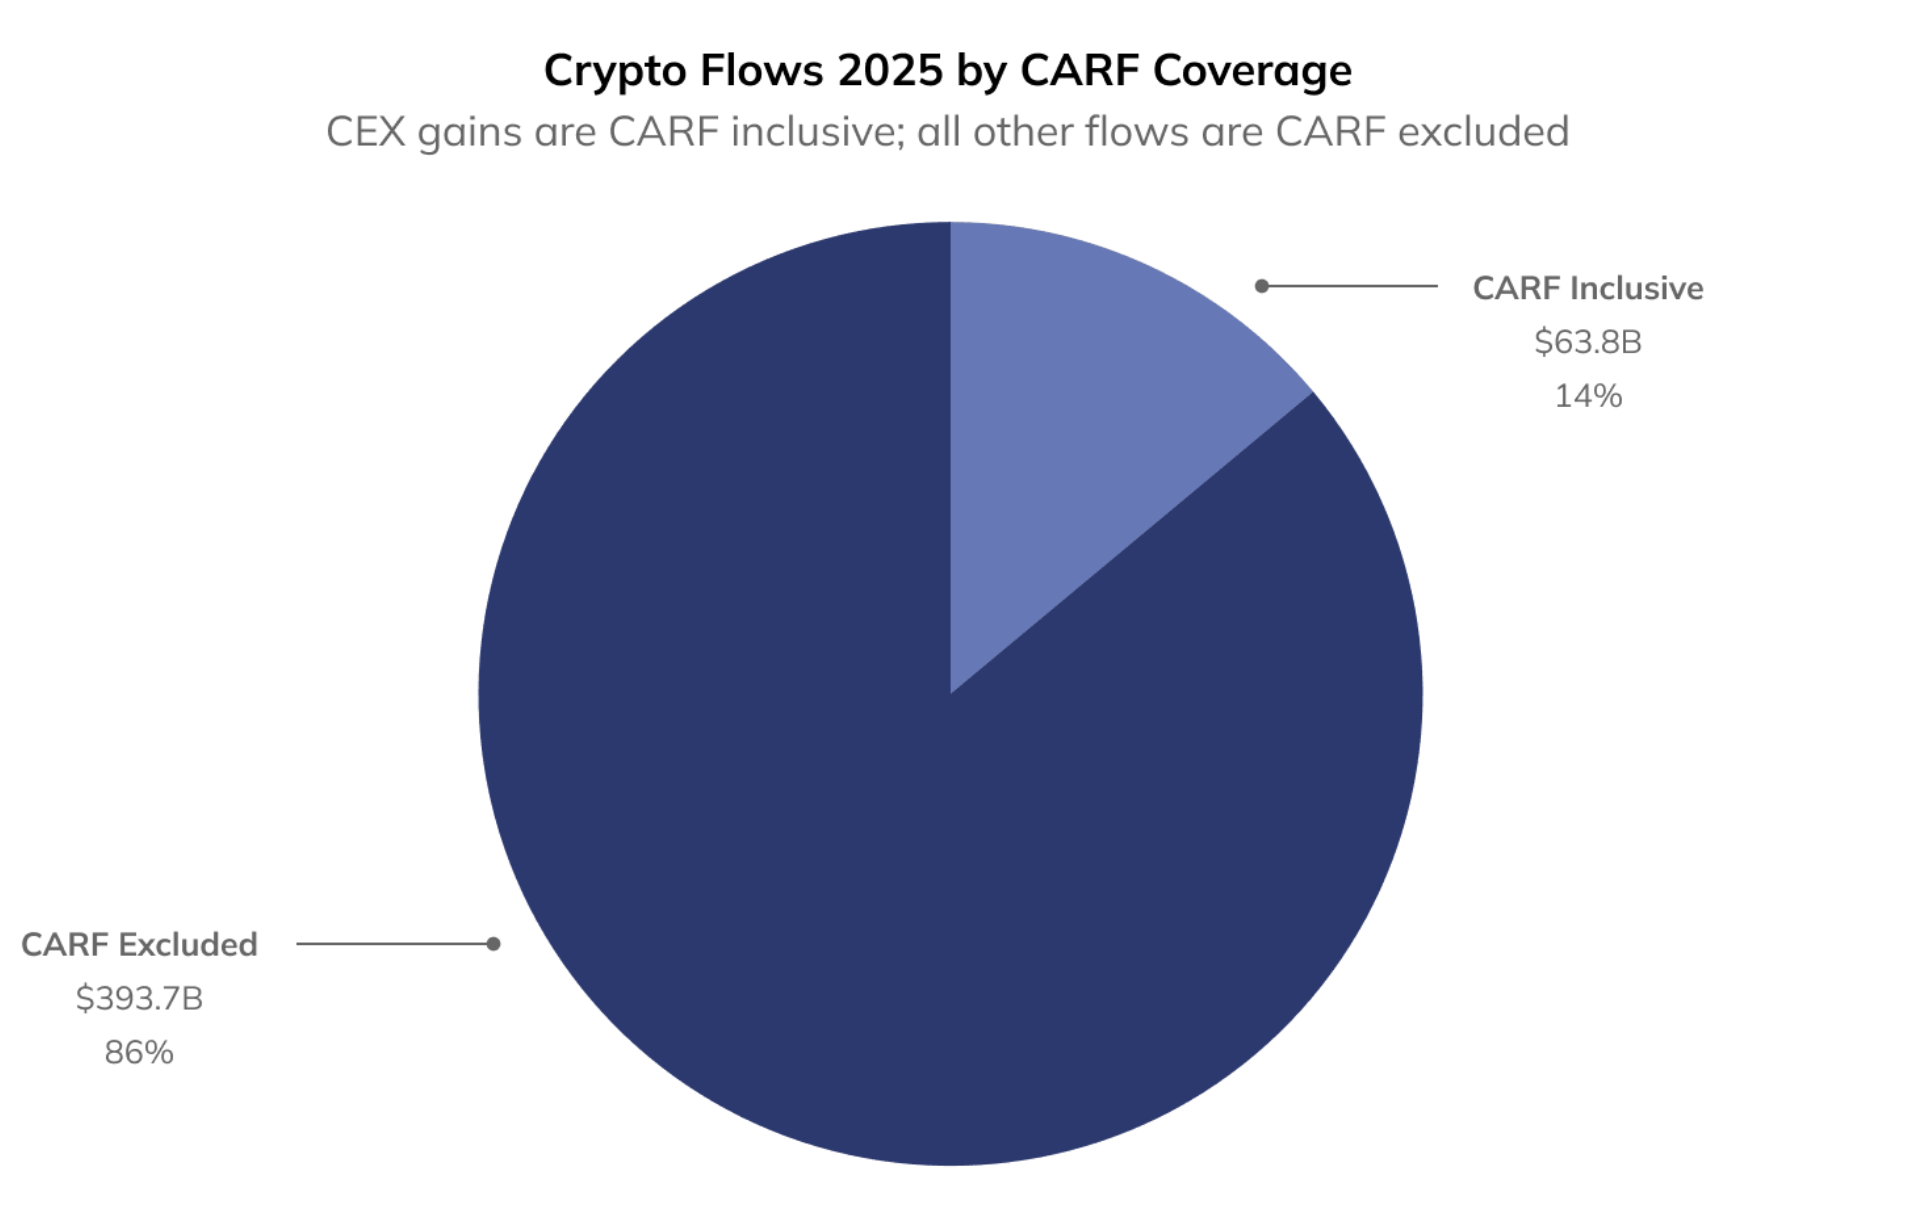
CARF covers solely 14% of doubtless taxable onchain crypto exercise. Supply: Chainalysis
Associated: Chainalysis sues US over $95M ICE contract with TRM Labs
CARF’s limits on onchain tax reporting
CARF information assortment started on Jan. 1, 2026, in 48 jurisdictions, together with the UK and European Union, requiring coated crypto platforms to gather further buyer and tax residency info.
Below CARF, in-scope crypto suppliers accumulate buyer and tax residency info and report transaction information to home tax authorities, which may then share that info throughout borders.
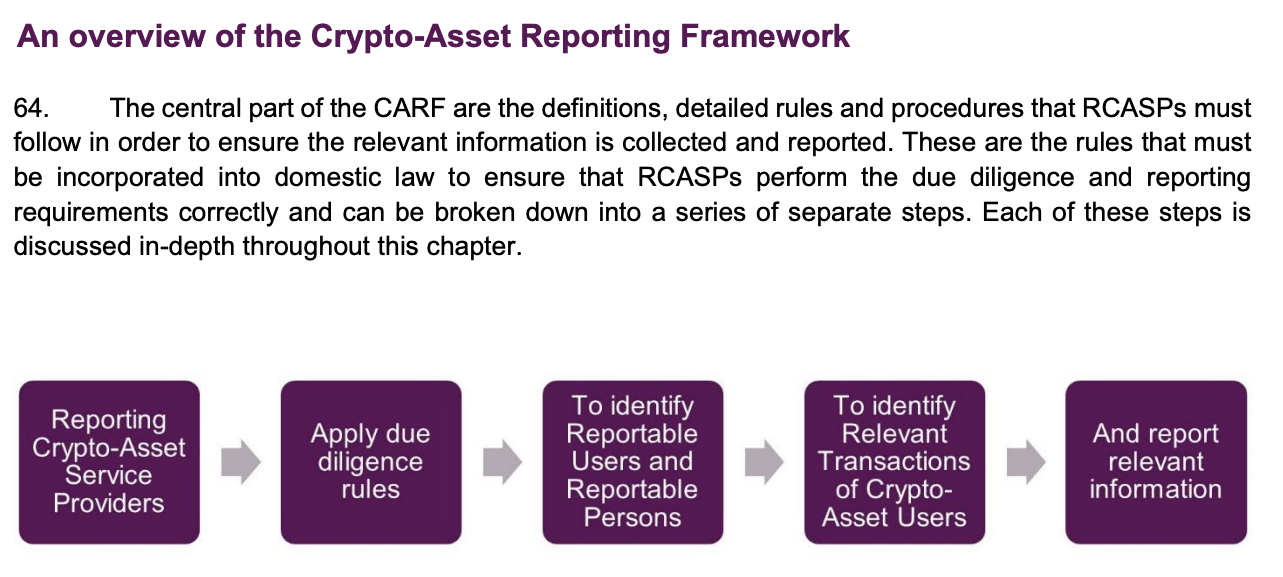
CARF framework. Supply: OECD
CARF’s deal with crypto intermediaries additionally helps clarify the gaps highlighted by Chainalysis. Colby Mangels, a former OECD adviser who labored on CARF, instructed Cointelegraph in January that the framework was designed round intermediaries that facilitate crypto transactions as a enterprise.
A lot of decentralized finance subsequently stays exterior the reporting perimeter, as there could also be no centralized operator or custodial relationship on which to impose reporting necessities.
That might change as regulators develop guidelines for decentralized platforms. Mangels stated tax authorities are watching developments in anti-money laundering regulation, together with efforts to find out when DeFi platforms or their operators must be handled as regulated crypto service suppliers.
Journal: SEC’s proposed crypto guidelines most likely gained’t spark new ICO growth

